

Payday Advance Borrow Money
4.7

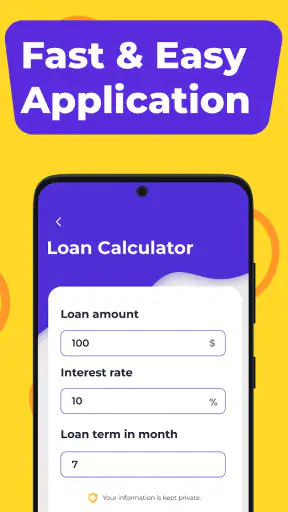
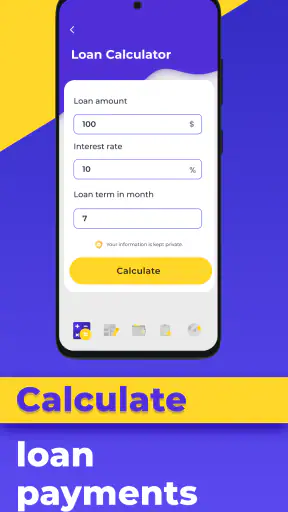
When money is tight, the hardest part is often not finding a loan app but understanding what you are agreeing to before you continue. I approached Payday Advance Borrow Money with that concern in mind. It is a finance app from Shpuryk Sergii that focuses on helping users find a suitable payday cash advance. The basic download is free, and the app is rated for Everyone, which makes it approachable at the store level. The more important question, though, is whether its presentation feels manageable when you are stressed, short on time, or using a phone in less-than-ideal conditions.
My overall impression is that this is best treated as a starting point for comparing borrowing possibilities, not as a complete financial safety net. It may be useful when you need to organize a search for short-term cash, but a payday advance can become expensive or difficult to repay if it is used casually. I would not open it with the assumption that an instant advance is automatically the right answer. I would open it with a repayment plan already in mind.
How clearly the app presents a borrowing search
Readability and navigation
The app’s purpose is easy to understand from the first encounter: it is built around finding a payday cash advance rather than managing a full bank account, tracking investments, or building a long-term budget. That narrow focus is helpful for someone who wants to move directly toward a borrowing search. It also means the experience should be judged by how well it helps a person pause, compare, and understand the next step instead of simply encouraging speed.
I find the short name and direct financial focus easier to process than a broad money-management app filled with unrelated tools. A person looking for emergency borrowing does not necessarily want charts, savings challenges, or a complicated dashboard. The trade-off is that a focused loan app can make the borrowing path feel more urgent than it really is. Clear navigation is valuable, but clarity should never be confused with affordability.
For readers who prefer larger text or who tire quickly while reading, the practical test is whether the important information remains understandable without rushing. Loan-related screens can contain conditions, repayment details, eligibility wording, and prompts that deserve careful reading. I recommend increasing the phone’s text size before beginning, using the device’s display settings rather than trying to skim. If a screen becomes crowded or a sentence is difficult to follow, stop there instead of relying on memory.
The app’s average rating is 4.7 from around 3.2 thousand ratings, with roughly 194 written reviews. That level of public response suggests that many people find the basic experience useful, but it should not be treated as proof that every borrower will receive the same result. A rating can describe convenience or ease of use; it cannot tell you whether a particular advance fits your income, repayment date, or local circumstances.
Why plain language matters more here than in ordinary shopping apps
In a shopping app, overlooking a small label may lead to an unwanted color or delivery option. In a borrowing app, overlooking a condition can affect your budget. That difference changes how I recommend using this product. Read each amount, date, fee, and repayment statement as though you were writing it down for someone else. If you cannot explain the total cost and the date money must be returned, you are not ready to accept an offer.
One useful workflow is to keep a note outside the app with four lines: the amount you need, the amount you expect to repay, the repayment date, and the money that will remain afterward. This is more reliable than switching between screens and trying to remember details. It also exposes a common problem with short-term borrowing: an advance can solve today’s shortage while creating a larger shortage on the next payday.
I would also avoid treating a prominent button as an instruction. A button that moves the process forward is not necessarily a recommendation that the offer is suitable. Take a moment to identify whether you are still browsing, submitting information, or accepting an agreement. That distinction is especially important for users with attention difficulties, reading fatigue, or anxiety around financial decisions.
Motor and sensory considerations
People use finance apps in very different physical conditions. Someone may have limited dexterity, tremors, reduced vision, hearing loss, or difficulty maintaining concentration. Someone else may simply be using one hand while commuting or holding a child. I cannot responsibly describe Payday Advance Borrow Money as having a particular accessibility certification or specialized assistive feature, so I judge it by how a careful phone setup and a slower workflow can support different needs.
For motor control, the safest approach is to avoid making important decisions while moving or while holding the phone awkwardly. Use both hands when entering sensitive details, enlarge the display if needed, and review each field before proceeding. If your device offers a confirmation delay, screen magnification, voice control, or an accessibility menu, those tools may make the interaction less error-prone. They are phone-level supports, not promises about the app itself, but they can make a meaningful difference.
For visual comfort, system text enlargement, bold text, increased contrast, and reduced brightness may help. Dark or light themes can affect people differently, especially in bright sunlight or at night. I would test the screen before entering financial information. A display that looks fine indoors may be hard to read outdoors, and glare can make a decimal point or date easy to miss.
For hearing-related needs, a finance workflow should not depend on audio alone. Keep the device’s captions, visual notifications, and vibration settings configured in a way that suits you, but still read the on-screen wording carefully. If an important instruction is unclear without sound, that is a reason to slow down and seek written clarification rather than guessing.
Sensory overload is another realistic concern. Financial urgency, repeated prompts, unfamiliar terminology, and a small screen can combine into a stressful experience. I would use the app in a quiet place, disable unrelated notifications temporarily, and complete one stage at a time. This is a small change, but it reduces the chance of tapping through a decision simply to make the discomfort stop.
Situational access: using it when life is already difficult
The most obvious use case is a sudden gap between an essential expense and the next income payment. Imagine a person whose car needs an urgent repair before work, with no savings available and no trusted family member able to help. This app may provide a structured place to investigate a payday advance instead of searching randomly across the web. Even in that situation, I would compare the repayment burden with alternatives before accepting anything.
Those alternatives might include asking the bill provider for an extension, checking an employer’s available wage-access option, contacting a community assistance service, or using a bank product with a lower overall cost. A loan search is not automatically the fastest solution once fees, eligibility checks, and repayment pressure are considered. The app is more useful when it helps you compare a borrowing route with those options, not when it becomes the only route you consider.
It may also suit someone who has difficulty organizing several possibilities independently. A dedicated payday-advance search can provide a more focused starting point than general web searches, which often mix advertisements, unrelated articles, and unclear application paths. The benefit is organizational: you can begin in one place. The limitation is that a focused search can narrow your thinking, so keep your broader options visible in a separate note.
Situational access includes language, stress, internet conditions, and privacy. If you are reading in a second language, do not rely on a quick translation of a crucial repayment clause. Use a trusted person or a reliable translation tool to understand the wording before accepting anything, while protecting your private financial details. If your connection is unstable, avoid repeatedly submitting forms; duplicate attempts can create confusion about what was completed.
Privacy also matters when using any borrowing service. I would not complete an application on public Wi-Fi or a shared device unless I could properly protect the screen and sign out afterward. Avoid photographing sensitive pages unless there is a clear reason to do so, and do not send personal financial information to someone who claims they can guarantee approval. The app can be a tool for finding an advance, but it cannot remove the risks that come with sharing financial information.
Remaining barriers before a user can make a sound decision
The largest barrier is not necessarily navigation; it is the nature of payday borrowing itself. Short-term credit can be tempting because the immediate need is visible while the later repayment pressure feels distant. A person with irregular income, existing debt, or no room in the next budget should be especially cautious. In those circumstances, a different route may be better, even if it takes more effort.
I would skip this app if you are looking for a long-term budgeting system, credit-building guidance, bill negotiation, or a complete overview of your finances. Its purpose is much narrower. A budgeting app, a credit-union conversation, or direct support from a financial counselor may be more appropriate when the problem is recurring rather than temporary.
I would also skip the borrowing process if you cannot identify exactly how repayment will happen. “I will work it out later” is not a repayment plan. Write down the expected income, essential bills, and the amount left after repayment. If that remainder would force you to borrow again, the advance is likely postponing the problem rather than solving it.
Another barrier is comparison quality. Finding an offer is not the same as finding a good offer. Examine the total repayment amount, all stated charges, the due date, consequences of late payment, and whether automatic withdrawals could interfere with essential bills. If any of these points are difficult to locate or understand, do not proceed until you have a clear explanation.
Because the app is free to install, the initial cost does not tell you the cost of borrowing. That distinction is easy to miss when a finance product is presented as a free download. I would separate the app’s access price from the financial product’s terms in my mind. The app may cost nothing to obtain while an advance still carries a substantial obligation.
The current release is version 1.2.1, and it supports devices running Android 5.0 or later. That broad device compatibility may help people using older phones, but an older operating system can have its own security and usability limitations. Keep the phone updated as far as the manufacturer allows, use a screen lock, and avoid storing sensitive screenshots. Compatibility makes installation possible; it does not guarantee that every device feels equally comfortable or secure.
Practical habits that make the experience safer and more inclusive
My first tip is to create a “pause point” before any final submission. After entering information, leave the screen for a few minutes, check your written budget, and return only when you can read the terms comfortably. This is particularly helpful for users with attention differences or anyone who tends to make quick decisions under pressure.
My second tip is to use a two-person review without surrendering control of your account. A trusted friend can read the repayment amount and due date aloud while you keep the phone in your hands. This can support people with dyslexia, low vision, or financial anxiety. Do not share passwords or verification codes, and do not let another person pressure you into accepting an offer.
My third tip is to compare the advance with the cost of not borrowing. If the expense is a utility bill, ask whether a payment arrangement would be cheaper. If it is a repair, ask whether a partial repair, public transport, or a delayed purchase changes the calculation. The app is most valuable when it fits into this decision process rather than replacing it.
My fourth tip is to save only the information you genuinely need for follow-up. A simple handwritten record of the provider, amount, repayment date, and total cost may be enough. Keeping fewer sensitive copies reduces exposure if your phone is lost or shared. At the same time, retain the documents necessary to understand your obligation and check your account for unexpected withdrawals.
Who will benefit, and who should choose another route
I can see the appeal for an adult who needs a focused way to explore a payday cash advance and prefers a dedicated finance app over a scattered search. The product has a clear niche, is free to download, and has attracted more than 100 thousand installs. Its Everyone age rating also makes the store entry broadly approachable, although the financial responsibility involved is clearly an adult concern in practice.
I would recommend caution for anyone with recurring cash shortages, unstable income, overdue debts, or difficulty reading financial conditions. I would also point people toward alternatives if they need ongoing money management rather than a short-term advance search. A bank or credit union may offer a more suitable conversation, while a budgeting tool may reveal that changing bill dates or reducing one expense solves the immediate gap.
The developer, Shpuryk Sergii, presents a narrowly defined finance product rather than a broad personal-finance platform. That specialization can reduce distraction, but it also means I would not expect it to replace independent research or financial advice. Use it as one step in a decision, not as an authority that determines what you can safely afford.
My inclusive verdict
Payday Advance Borrow Money is accessible in the everyday sense that its purpose is easy to identify and its focused format may be less intimidating than a large financial platform. With device-level text, contrast, magnification, and input tools, many users can adapt the experience to their needs. Those supports are useful, but they do not remove the need to read carefully or confirm every borrowing condition.
Its strongest role is helping a person begin a targeted search when a short-term cash gap feels urgent. Its weakest point is the risk that convenience encourages a decision before the repayment consequences are understood. That is why I would use it slowly, with a written budget, a comparison against non-loan options, and a clear stopping rule.
My recommendation is conditional: consider it if you need a focused payday-advance search and already know how repayment will fit into your budget. Choose another option if your shortage is ongoing, if the terms are hard to read, or if repaying would trigger another emergency. The app can make the search more organized, but the inclusive and responsible choice is the one that leaves you able to manage the days after the advance arrives.
4.7
194.00 Reviews
Pros
- Quick application process with clear borrowing steps
- Useful for covering urgent
- short-term expenses
- Loan details are presented before accepting an offer
- Accessible option for users with limited traditional credit
- Simple interface makes account management easy
Cons
- Interest and fees can make repayment significantly more expensive
- Short repayment periods may strain your budget
- Approval and loan terms may vary by applicant
- Late payments could lead to additional charges or credit impact
- Availability and lending rules depend on your location


